Gross vs Net Rental Yield: What’s the Difference?
If you are researching an investment property, rental yield is one of the first numbers you will encounter. But two figures can appear for the same property: gross rental yield and net rental yield.
Understanding gross vs net rental yield matters because the two calculations answer different questions. Gross yield shows the rental income generated before property expenses. Net yield goes further by accounting for ongoing costs.
A property may look attractive based on its gross yield but produce a considerably smaller return after management fees, insurance, maintenance, vacancy, council rates, strata costs, and other expenses.
In this guide, you will learn how both yields work, how to calculate them, and what to consider when comparing rental properties.
What Is Rental Yield?
Rental yield is a percentage that measures the rental income a property generates relative to its value or acquisition cost.
It is commonly used by property investors as a quick way to assess rental income. However, yield is only one part of an investment analysis. Property investors may also consider capital growth, financing costs, vacancy risk, location, maintenance requirements, and other factors.
There are two common approaches:
- Gross rental yield—rental income before operating expenses.
- Net rental yield—rental income after specified property expenses.
Realestate.com.au describes gross yield as annual rental income divided by property value, while its net-yield calculation subtracts annual expenses before dividing by property value.
Gross vs Net Rental Yield: The Key Difference
The simplest way to understand gross vs net rental yield is to think about income before and after expenses.
Gross rental yield answers:
How much rental income does this property generate compared with its value before expenses?
Net rental yield answers:
How much rental income remains after relevant property expenses?
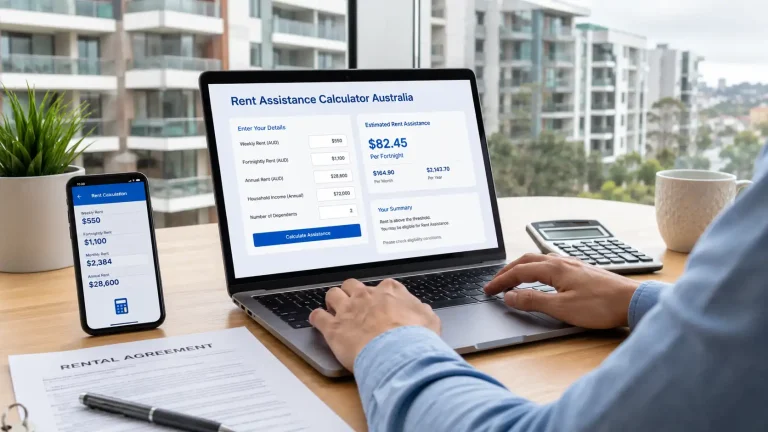
For example, imagine a property worth $500,000 that rents for $550 per week.
Annual rent is
$550 × 52 = $28,600
The gross rental yield is
$28,600 ÷ $500,000 × 100 = 5.72%
At first glance, a 5.72% yield may look useful for comparing properties. But the landlord still has expenses to pay.
Suppose eligible annual operating expenses total $7,000.
Net rental income becomes:
$28,600 − $7,000 = $21,600
The indicative net yield is
$21,600 ÷ $500,000 × 100 = 4.32%
The difference between 5.72% and 4.32% shows why looking at gross vs net rental yield can produce very different impressions of the same property.
How to Calculate Gross Rental Yield
Gross rental yield is relatively straightforward.
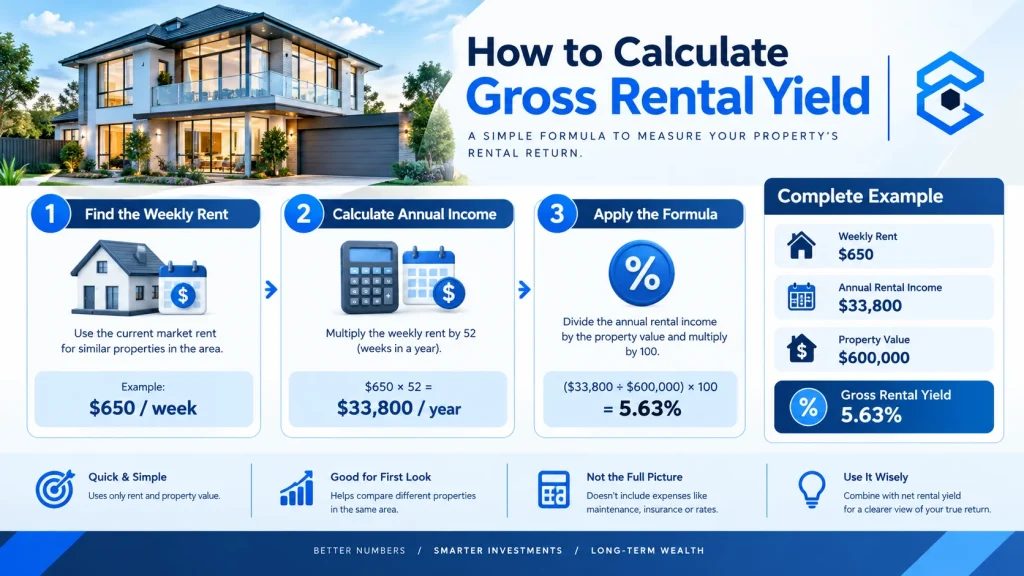
Gross Rental Yield Formula
Gross Rental Yield = (Annual Rental Income ÷ Property Value) × 100
If you know the weekly rent, first convert it into annual rental income:
Annual Rental Income = Weekly Rent × 52
For example:
- Property value: $600,000
- Weekly rent: $650
- Annual rent: $650 × 52 = $33,800
Now calculate the yield:
$33,800 ÷ $600,000 × 100 = 5.63%
The property’s gross rental yield is approximately 5.63%.
This calculation is useful because it is quick and requires relatively few assumptions. It can help investors compare properties at an early stage.
However, gross yield does not show what remains after operating costs.
How to Calculate Net Rental Yield
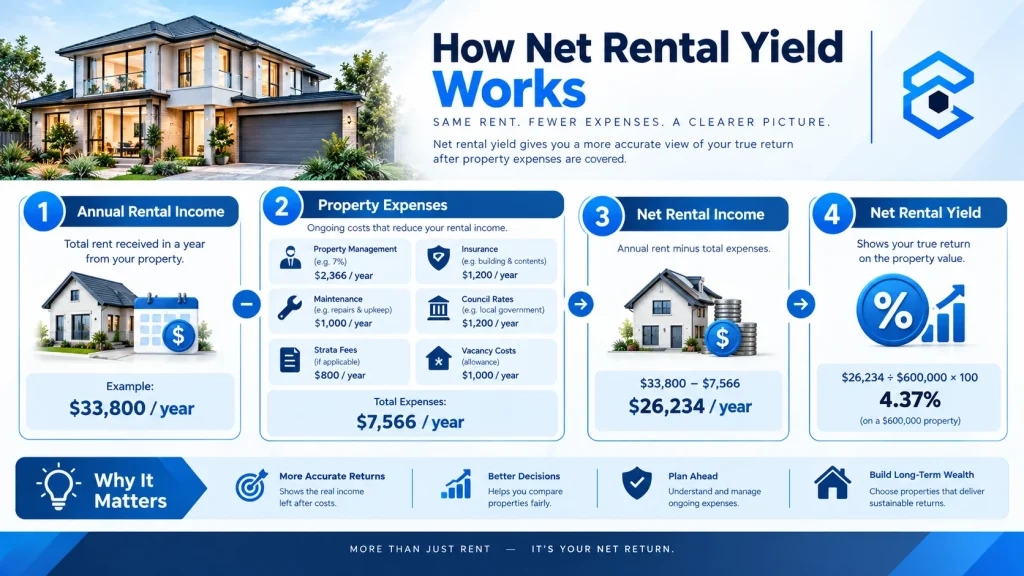
Net rental yield requires more information because you need to estimate or identify the property’s expenses.
Net Rental Yield Formula
Net Rental Yield = [(Annual Rental Income − Annual Property Expenses) ÷ Property Value] × 100
Consider the same $600,000 property earning $33,800 in annual rent.
Suppose its annual expenses include:
- Property management: $2,500
- Insurance: $1,400
- Maintenance: $2,000
- Council rates: $2,200
- Other operating expenses: $900
Total expenses:
$9,000
Net rental income:
$33,800 − $9,000 = $24,800
Net rental yield:
$24,800 ÷ $600,000 × 100 = 4.13%
So the property has:
Gross yield: 5.63%
Net yield: 4.13%
This example demonstrates why gross vs net rental yield should not be treated as interchangeable measures.
What Expenses Affect Net Rental Yield?
The exact expenses included in a net-yield calculation can vary depending on the purpose of the calculation and the property.
Common operating expenses can include:
Property Management Fees
If you use a professional property manager, management fees can reduce the income you retain from rent.
Insurance
Landlord insurance and other relevant property insurance costs may form part of the property’s annual expenses.
Maintenance and Repairs
Properties require ongoing maintenance. Plumbing problems, appliance repairs, painting, gardening, and other work can affect annual returns.
Council Rates
For many properties, the owner is responsible for council rates and related charges.
Strata or Body Corporate Fees
Apartment and unit owners may have recurring strata or body corporate expenses. These can make a substantial difference to the net return.
Vacancy
A property does not necessarily remain occupied every week of the year. Periods without rental income can reduce the actual annual return.
Other Property Costs
Depending on the property, investors may also need to consider advertising, accounting, utilities paid by the owner, pest control, and other recurring costs.
The important point is consistency. When comparing two properties, use comparable expense assumptions rather than including major costs for one property and ignoring them for another.
Why Gross Rental Yield Is Still Useful
If net yield provides more detail, why calculate gross yield at all?
Gross yield is useful because it is quick.
When screening a large number of properties, you may not have complete information about every expense. Gross yield can provide an initial comparison before you conduct deeper due diligence.
Realestate.com.au also notes that gross rental yield can be a useful starting point when assessing investment properties, while pointing out that yield alone does not capture every aspect of an investment.
For example, an investor might compare:
| Property | Annual Rent | Property Value | Gross Yield |
|---|---|---|---|
| A | $30,000 | $500,000 | 6.00% |
| B | $32,000 | $600,000 | 5.33% |
| C | $35,000 | $700,000 | 5.00% |
This gives you a quick starting point.
But it does not tell you which property has the lowest expenses or the highest income after costs.
That is where net yield becomes useful.
Why Net Rental Yield Can Give a Different Picture
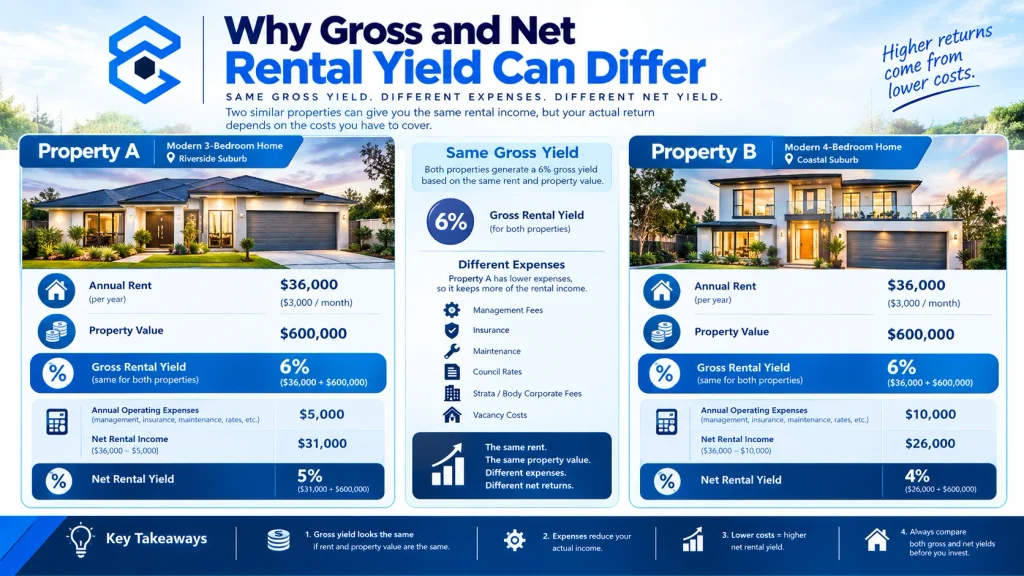
Consider two properties with the same gross yield.
Property A
- Annual rent: $30,000
- Value: $500,000
- Gross yield: 6%
- Annual operating expenses: $5,000
- Net income: $25,000
- Net yield: 5%
Property B
- Annual rent: $30,000
- Value: $500,000
- Gross yield: 6%
- Annual operating expenses: $10,000
- Net income: $20,000
- Net yield: 4%
Both properties have a 6% gross yield.
But their net yields are different.
This is the practical reason to examine gross vs net rental yield rather than relying on a single headline percentage.
A property with significant strata fees, frequent maintenance, high management costs, or regular vacancy can have a much smaller income return after expenses.
Does Net Rental Yield Include Mortgage Interest?
This is an important distinction.
There is no single universal convention for every rental-yield calculation. Whether mortgage interest is included depends on the methodology being used.
A basic net rental yield calculation generally focuses on property operating expenses. If you include financing costs, you are moving toward a cash-flow or cash-on-cash analysis rather than simply comparing operating rental yields.
For that reason, always check what someone means when they report a “net yield.”
Two investors can calculate different numbers because they have included different categories of expenses.
Gross vs Net Rental Yield: Which One Should You Use?
The answer depends on what you are trying to understand.
Use gross rental yield when you want a quick initial comparison.
For example, you could use gross yield while screening properties across different suburbs or price ranges.
Use net rental yield when you want to understand the income remaining after operating expenses.
A sensible property analysis can use both.
Start with gross yield to narrow your options. Then investigate the property’s expenses and calculate a more realistic net figure.
This two-stage approach helps prevent a high headline yield from becoming the only factor in your analysis.
Gross Yield vs Net Yield Example
Let’s put everything together.
Suppose you are considering a property priced at $750,000.
The expected rent is $750 per week.
Annual rental income:
$750 × 52 = $39,000
Gross Yield
$39,000 ÷ $750,000 × 100 = 5.20%
So the gross rental yield is 5.20%.
Now assume annual operating expenses are
- Management: $3,000
- Insurance: $1,600
- Council rates: $2,500
- Maintenance: $2,400
- Other expenses: $1,000
Total expenses:
$10,500
Net rental income:
$39,000 − $10,500 = $28,500
Net yield:
$28,500 ÷ $750,000 × 100 = 3.80%
The property therefore has a 5.20% gross yield and a 3.80% net yield under these assumptions.
The gap is significant.
That gap is essentially showing how much the selected operating expenses reduce the property’s rental income.
Common Mistakes When Calculating Rental Yield
Using Monthly Rent Without Converting It Correctly
If rent is quoted weekly, multiply it by 52 for an annual estimate.
Forgetting Property Expenses
This can make the expected return look higher than the income actually remaining after operating costs.
Ignoring Vacancy
A property that is vacant for several weeks does not generate a full year’s rent.
Mixing Different Property Values
Be consistent when comparing properties. Using a purchase price for one property and a current market value for another can produce figures that are not directly comparable.
Treating Yield as the Entire Investment Return
Rental yield focuses on rental income. It does not by itself capture capital growth, taxes, financing structure, transaction costs, or every aspect of investment performance.
MoneySmart notes that property investment involves both potential rental income and capital growth, along with costs and other considerations.
Is a Higher Rental Yield Always Better?
Not necessarily.
A higher rental yield tells you that the relationship between rental income and property value is higher under the calculation being used. It does not automatically mean the property is the right investment for every investor.
Location, tenant demand, vacancy, property condition, future expenses, financing, and potential capital growth can all matter.
For example, two properties could have similar yields but very different maintenance requirements.
Therefore, use yield as one measurement within a broader property-investment analysis.
How to Compare Rental Properties More Effectively
If you are comparing several investment properties, consider following a consistent process:
Step 1: Calculate annual rental income.
Weekly rent × 52.
Step 2: Calculate gross yield.
Annual rent ÷ property value × 100.
Step 3: Estimate operating expenses
Include relevant recurring costs and reasonable vacancy assumptions.
Step 4: Calculate net rental income.
Annual rent − relevant expenses.
Step 5: Calculate net yield.
Net rental income ÷ property value × 100.
Step 6: Investigate the property beyond yield.
Look at location, rental demand, vacancy, property condition, financing, and other investment factors.
This gives you a more complete picture than looking at a single percentage.
Gross vs Net Rental Yield: Final Takeaway
The main difference between gross vs net rental yield is the treatment of expenses.
Gross yield measures rental income before operating expenses. Net yield subtracts relevant property expenses before calculating the percentage.
Gross yield is useful for quick comparisons. Net yield provides a more expense-aware view of the property’s rental income.
If you are researching an investment property, calculate both rather than relying on a headline yield alone. Then examine the assumptions behind the numbers.
Most importantly, remember that rental yield is a measurement of rental income, not a complete prediction of investment performance.
A careful property analysis should consider income, expenses, vacancy, financing, taxes, property condition, and potential capital growth before you make an investment decision.
Frequently Asked Questions
What is the difference between gross and net rental yield?
Gross rental yield measures annual rental income against the property’s value before operating expenses. Net rental yield subtracts relevant property expenses before calculating the yield.
How do you calculate gross rental yield?
Use this formula:
Gross Rental Yield = (Annual Rental Income ÷ Property Value) × 100
For weekly rent, multiply the weekly amount by 52 to estimate annual rental income.
How do you calculate net rental yield?
Use:
Net Rental Yield = [(Annual Rental Income − Annual Property Expenses) ÷ Property Value] × 100
The exact expenses included should be clearly defined and applied consistently.
Is gross rental yield higher than net rental yield?
Usually, yes, when the net calculation subtracts positive operating expenses from rental income. The difference depends on the property’s costs.
Should I compare properties using gross or net yield?
Gross yield can be useful for initial screening, while net yield can provide more insight into income after operating expenses. Using both can give you a broader view.
Does rental yield include capital growth?
No. Rental yield measures rental income relative to property value or cost. Capital growth is a separate component of potential property investment returns.