Mortgage Calculator USA: The Ultimate Step-by-Step Guide for 2026
Buying a home can feel like a giant math problem wearing a nice front door.
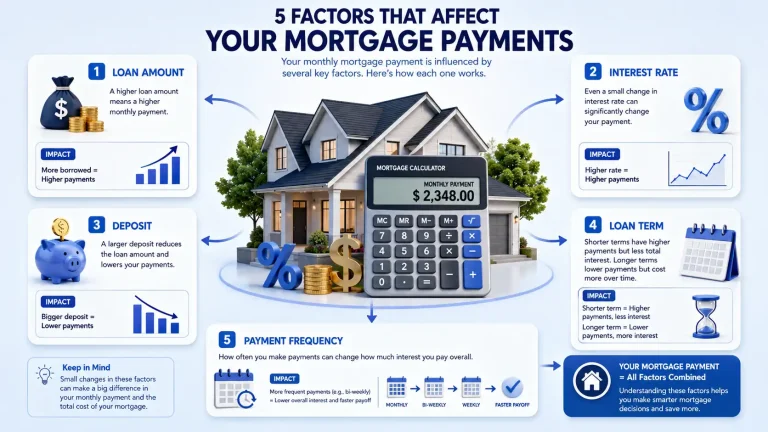
You have the home price, down payment, interest rate, loan term, property taxes, insurance, and sometimes HOA fees. Miss one piece, and your “affordable” home can suddenly become much more expensive.
A mortgage calculator USA helps turn those numbers into a practical monthly payment estimate. You can use it before shopping for a house, comparing loan options, checking affordability, or deciding whether extra payments could save you money.
In this guide, you’ll learn how mortgage payments work, how much house you may be able to afford, how extra payments change your loan, and why California, Texas, Florida, New York, and other states can produce very different results.
You’ll also see how to use mortgage calculations more intelligently instead of blindly trusting one number.
Quick Answer: A mortgage calculator in the USA estimates your monthly mortgage cost from the loan amount, interest rate, and repayment term. A more complete estimate can also include property taxes, homeowners insurance, mortgage insurance, and HOA fees. Use it for planning, then confirm the final numbers with your lender and loan estimate.
What Is a Mortgage Calculator USA, and How Does It Work?
A mortgage calculator USA is an online tool that estimates what you may pay each month for a home loan. The basic calculation uses three major inputs: loan principal, interest rate, and loan term.
The principal is the amount you borrow. The interest rate is the lender’s charge for borrowing that money. The term tells you how long you have to repay the loan.
For a typical fixed-rate mortgage, the monthly principal-and-interest payment stays the same. However, the amount going toward principal and interest changes over time.
The Consumer Financial Protection Bureau explains that mortgage payments often include more than principal and interest. Property taxes, homeowners insurance, and mortgage insurance may also affect the total monthly cost.
What Does the Calculator Usually Include?
A useful calculator may ask for:
- Home purchase price
- Down payment
- Mortgage loan amount
- Interest rate
- Loan term
- Property taxes
- Homeowners insurance
- PMI or mortgage insurance
- HOA or condo fees
- Extra monthly payments
That matters because a $2,500 principal-and-interest payment does not necessarily mean your housing bill will be $2,500.
Your real monthly housing cost could be higher.
Direct Answer: A mortgage calculator in the USA estimates your mortgage payment by combining your loan amount, interest rate, and repayment period, with advanced tools adding taxes, insurance, and other housing costs.
Key Takeaway
- Start with principal, rate, and term.
- Add taxes, insurance, PMI, and HOA costs for a better estimate.
- Treat the result as a planning figure, not a loan approval.
The important lesson is simple: calculate the whole housing cost, not just the loan payment.
How Do You Calculate a Mortgage Payment in the USA?
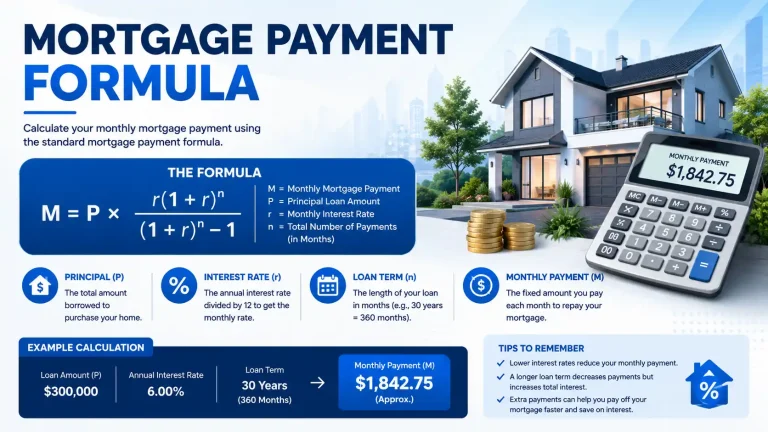
A mortgage calculator USA uses a standard amortization formula for most fixed-rate loans. You do not need to perform the formula manually, but understanding it helps you spot unrealistic estimates.
The standard formula is
M = P × [r(1 + r)ⁿ] ÷ [(1 + r)ⁿ − 1]
Here:
- M = monthly principal and interest payment
- P = loan principal
- r = monthly interest rate
- n = total number of monthly payments
Suppose you borrow $400,000 for 30 years at a hypothetical 7.28% fixed interest rate. That rate matches Freddie Mac’s October 1, 2026 reported average 30-year fixed mortgage rate.
The estimated principal-and-interest payment would be about $2,737 per month.
But wait. That is not necessarily your final housing payment.
Property taxes and insurance could push the number higher.
Example: A $400,000 Mortgage
| Loan detail | Example |
|---|---|
| Loan amount | $400,000 |
| Interest rate | 7.28% |
| Loan term | 30 years |
| Monthly principal + interest | About $2,737 |
| Number of payments | 360 |
| Estimated interest over full term | About $585,266 |
This example shows why the interest rate matters so much.
The lower your rate, the less interest you generally pay over the life of the loan, assuming the other loan terms stay unchanged.
The reverse is also true.
A small rate difference can become a surprisingly large dollar amount over 30 years.
Why Does Amortization Matter?
Amortization describes how your mortgage balance falls over time.
Early in the loan, a larger share of each principal-and-interest payment goes toward interest because the outstanding balance is still high. As the balance falls, more of the payment goes toward principal.
That is why making additional principal payments early can have a bigger long-term impact than many borrowers expect.
Direct Answer: Your mortgage payment comes from a standard amortization formula, but your actual housing cost can be higher after taxes, insurance, PMI, and other charges.
Key Takeaway
- The interest rate strongly affects your payment.
- A 30-year term usually creates a lower payment than a 15-year term.
- Amortization causes the balance between interest and principal to change over time.
Understanding amortization makes mortgage calculators much easier to use correctly.
How Much House Can I Afford With a Mortgage Calculator USA?
A mortgage calculator USA can estimate payments, but affordability is a bigger question.
Your lender will look at income, debts, credit history, assets, loan type, down payment, and other factors. You should do the same before falling in love with a house that looks perfect online.
Fannie Mae notes that a general housing budget may fall around 25% to 30% of gross income, although personal circumstances can vary considerably.
That is not a universal approval rule.
It is a budgeting starting point.
What Should You Include in Your Budget?
Before deciding how much you can borrow, consider:
- Gross monthly income
- Car loans
- Student loans
- Credit card payments
- Childcare costs
- Utilities
- Insurance
- Property taxes
- Home maintenance
- HOA fees
- Emergency savings
Here’s the thing: lenders calculate whether you can qualify. You need to decide whether the payment fits your actual life.
Those are not always the same question.
Mortgage Affordability vs. Mortgage Eligibility
A mortgage affordability calculator USA can help estimate a comfortable price range.
A mortgage eligibility calculator in the USA focuses more on whether your financial profile may fit certain lending requirements.
Neither tool guarantees approval.
For example, you might technically qualify for a $500,000 home but feel much more comfortable buying a $375,000 property.
That extra breathing room can matter when your roof needs work, your car breaks down, or your property tax bill jumps.
Direct Answer: You can estimate affordability by comparing your income and existing debts with the complete monthly cost of owning the home.
Key Takeaway
- Qualification and affordability are different.
- Include debts and everyday expenses before setting your price range.
- Leave room for repairs, emergencies, and changing housing costs.
A smart home budget leaves room for real life, not just the lender’s calculator.
How Does a Mortgage Calculator USA With Extra Payments Work?
A mortgage calculator USA with extra payments shows what happens when you pay more than the scheduled monthly amount.
This is where mortgage math gets interesting.
Suppose you have the same hypothetical $400,000 loan at 7.28% for 30 years. The regular principal-and-interest payment is about $2,737.
Now imagine adding $300 per month toward principal.
Your payment becomes roughly $3,037 for principal and interest.
Under this simplified example, the loan could be paid off roughly 95 months earlier, or nearly 7 years and 11 months sooner. The estimated interest savings would be substantial, although actual lender calculations can vary based on payment timing and loan terms.
That is a serious difference for $300 a month.
How to Make Extra Payments Work
Before sending extra money, check your mortgage documents.
You want to know:
- Whether your loan has any prepayment penalty.
- How your lender applies additional payments.
- Whether you can specify that extra money goes toward principal.
- Whether your regular payment schedule changes after an extra payment.
- Whether another use for the cash makes more financial sense.
Do not assume every extra payment automatically works the same way.
If your lender accepts principal-only payments, even small recurring amounts can reduce the balance faster.
Is Overpaying Always the Best Choice?
Not necessarily.
You may have higher-interest credit card debt, limited emergency savings, or other financial goals that deserve attention first.
There is also an opportunity cost.
Money used to reduce a mortgage cannot simultaneously sit in your emergency fund or be invested elsewhere.
A mortgage overpayment calculator USA is useful because it lets you compare different scenarios before making that decision.
Direct Answer: Extra mortgage payments can shorten your repayment period and reduce interest, but you should compare the benefit against your other financial priorities.
Key Takeaway
- Extra principal payments can reduce interest.
- Even a few hundred dollars monthly can change the payoff timeline.
- Check your loan terms before making large additional payments.
The best overpayment plan is one you can maintain without wrecking your cash reserves.
Why Are Mortgage Rates and Loan Terms So Important?
Your mortgage rate can dramatically change the amount you pay over time.
Freddie Mac reported a 7.28% average 30-year fixed mortgage rate on October 1, 2026, while its 15-year average stood at 6.60% that week.
Rates move.
They can change because of economic conditions, inflation expectations, bond-market movements, lender pricing, and other factors.
That is why a current mortgage calculator USA should use a rate that reflects your actual quote rather than an old internet example.
15-Year vs. 30-Year Mortgage
A 15-year loan normally has a higher monthly principal-and-interest payment.
But you repay the debt much faster and generally pay less interest over the full term.
A 30-year loan usually provides a lower monthly payment.
The trade-off is a longer repayment period and potentially much more total interest.
| Feature | 15-Year Mortgage | 30-Year Mortgage |
|---|---|---|
| Monthly payment | Usually higher | Usually lower |
| Payoff period | 15 years | 30 years |
| Total interest | Usually lower | Usually higher |
| Cash-flow flexibility | Lower | Higher |
| Equity buildup | Faster | Slower |
Neither option automatically wins.
The right choice depends on your income, goals, savings, and tolerance for a larger monthly payment.
Direct Answer: Interest rate and loan term directly affect your monthly payment and the total interest paid over the life of the mortgage.
Key Takeaway
- Compare rates using the same loan amount and term.
- A shorter loan can reduce total interest.
- A longer loan can provide more monthly breathing room.
Never compare mortgages using the monthly payment alone; compare the full cost.
Does a Mortgage Calculator USA Change by State?
Yes.
The basic mortgage formula does not suddenly become different when you cross a state line.
But the total cost of owning the property can change substantially.
Property taxes, homeowners insurance, local housing prices, HOA costs, and other expenses vary by location.
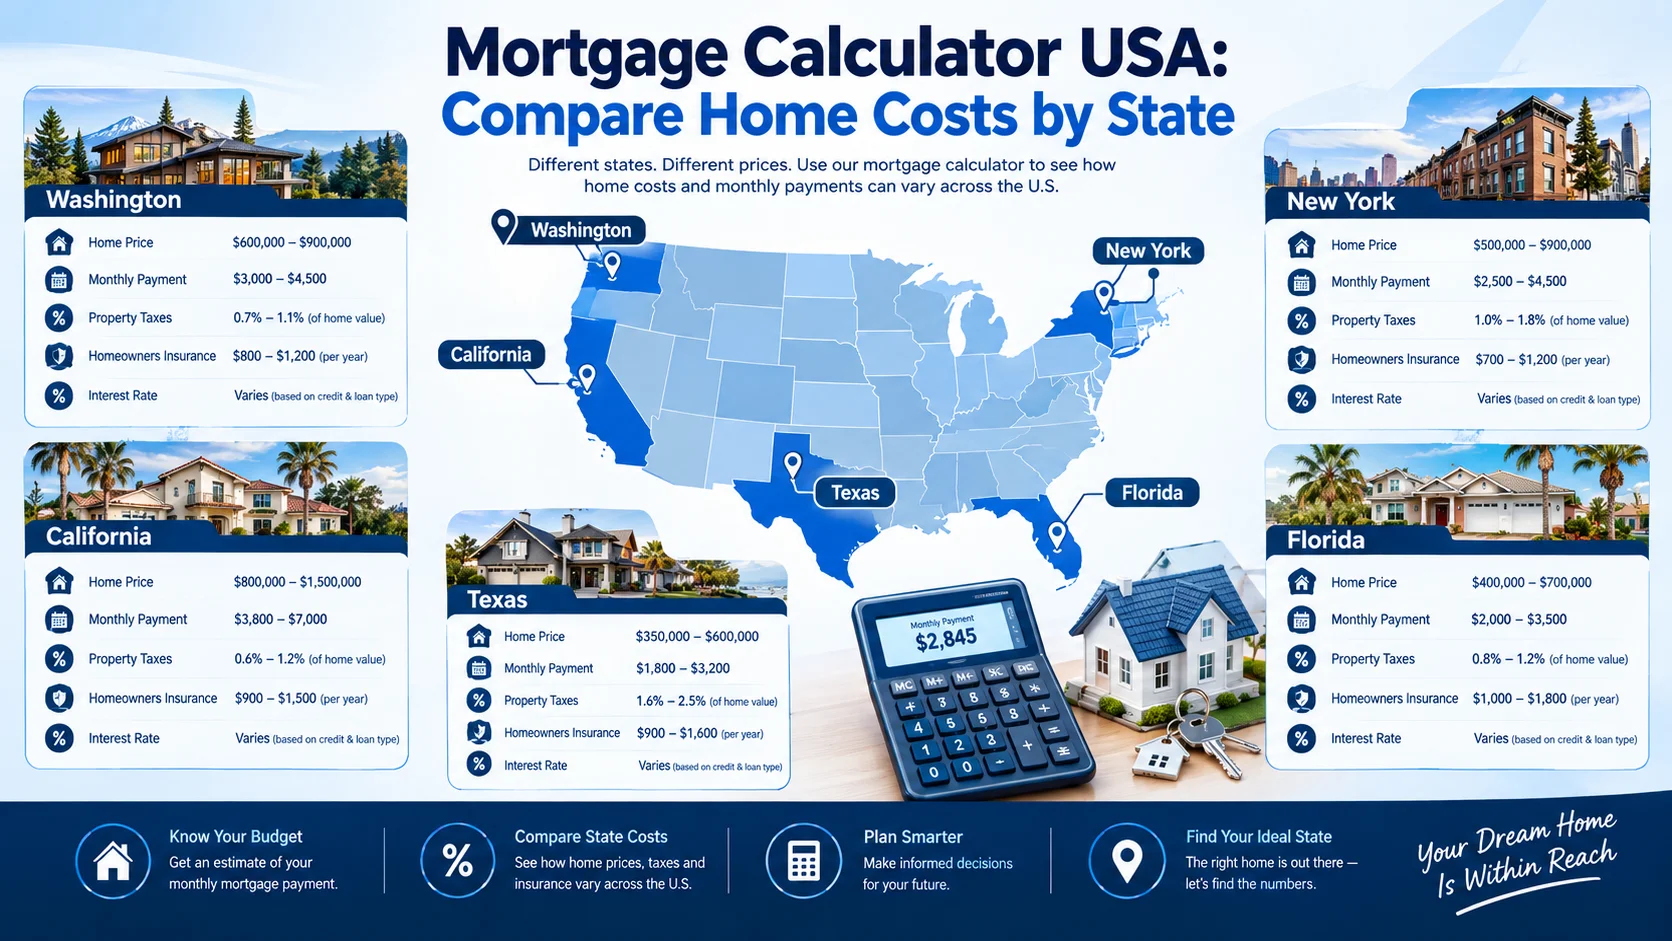
That is why searches such as mortgage calculator USA Florida, mortgage calculator USA Texas, mortgage calculator USA California, mortgage calculator USA Washington State, and mortgage calculator USA New York can produce very different practical results.
Florida
Florida buyers may need to pay close attention to homeowners insurance and property taxes. Insurance costs can have a meaningful effect on the total monthly housing budget.
Texas
Texas has no state individual income tax, but property taxes can be significant. A calculator that ignores property taxes can therefore paint an incomplete picture.
California
California home prices can be high, making the loan amount a major factor. Property taxes, insurance, HOA fees, and local market conditions should all be considered.
Washington State
Washington buyers should also look beyond principal and interest. Property taxes, insurance, and local home prices affect the final affordability picture.
New York
New York has major differences between markets. Buying in New York City is a completely different financial exercise from buying in a smaller upstate market.
The same $400,000 mortgage can therefore have a very different total housing cost depending on where the property sits.
Direct Answer: The mortgage formula stays broadly consistent across the USA, but taxes, insurance, home prices, and local fees can change your real monthly cost.
Key Takeaway
- State location affects the total cost of homeownership.
- Add local taxes and insurance to your estimate.
- Do not compare states using principal and interest alone.
Location can change affordability even when the mortgage amount stays exactly the same.
Which Mortgage Calculator USA Should You Use for Different Loans?
Not every borrower needs the same type of calculator.
A house mortgage calculator USA works well for a standard residential purchase. But specialized situations call for different inputs.
A commercial mortgage calculator USA may be more appropriate for business property financing.
A refinance mortgage calculator USA can compare your existing loan with a proposed replacement mortgage.
An interest only mortgage calculator USA estimates payments when the loan structure allows interest-only payments for a specified period.
An Islamic mortgage calculator USA may be useful for consumers researching Sharia-compliant home financing structures, although these products can use different contractual arrangements from conventional interest-bearing mortgages.
What About Car Mortgages?
The phrase car mortgage calculator USA is unusual because vehicles are generally financed with auto loans rather than mortgages.
If you are calculating a vehicle payment, use an auto loan calculator instead.
What About Business Loans?
A business mortgage calculator USA may refer to commercial property financing rather than a normal residential mortgage.
Commercial loans can have different terms, rates, repayment structures, and underwriting standards.
So don’t force every loan into a residential mortgage calculator.
Direct Answer: Choose a calculator that matches the type of financing you are actually considering because different loans can use different terms and costs.
Key Takeaway
- Residential mortgages need residential mortgage calculations.
- Refinancing requires a comparison of old and new loan costs.
- Commercial and specialized financing may need different tools.
The right calculator is the one built for the loan you actually plan to use.
How Can You Use a Mortgage Calculator USA Before Applying?
The smartest time to use a mortgage calculator USA is before you submit a mortgage application.
It gives you a rough financial map before a lender provides formal numbers.
Try this simple process.
Step 1: Start With the Home Price
Enter the price of the property you are considering.
Do not start with the maximum amount a lender says you can borrow.
Start with a price you can realistically afford.
Step 2: Enter Your Down Payment
A larger down payment generally means a smaller mortgage.
For example, a $500,000 home with a $100,000 down payment creates a $400,000 loan before considering other adjustments.
Your down payment can also affect mortgage insurance requirements and the amount of equity you start with.
Step 3: Add Your Interest Rate
Use your lender’s quoted rate when you have one.
If you do not have a quote yet, use a reasonable market estimate and label the result as an estimate.
Do not treat a rate shown in an old article as today’s guaranteed rate.
Step 4: Compare Loan Terms
Run both 15-year and 30-year scenarios if you qualify for them.
Then compare:
- Monthly payment
- Total interest
- Payoff date
- Cash-flow requirements
Step 5: Add Taxes and Insurance
This is where a basic calculator can become much more useful.
The CFPB warns that the total mortgage payment can include taxes, homeowners insurance, and mortgage insurance.
Fannie Mae’s calculator also allows users to account for property taxes, homeowners insurance, and HOA or condo fees.
Step 6: Test Extra Payments
Try an additional $100, $250, $500, or another amount you could realistically afford.
Watch what happens to the payoff timeline and interest cost.
Step 7: Compare the Result With Your Budget
Finally, compare the estimated payment with your income, debts, savings, and normal spending.
If the payment looks uncomfortable, lower the purchase price.
That’s not failure.
That’s good financial planning.
Direct Answer: Use a mortgage calculator before applying to test loan amounts, rates, terms, taxes, insurance, and extra payments against your real budget.
Key Takeaway
- Run several scenarios instead of trusting one result.
- Use your lender’s rate when available.
- Compare the result with your full household budget.
A calculator becomes powerful when you use it to test decisions rather than justify them.
What Are the Biggest Mortgage Calculator Mistakes to Avoid?
The biggest mistake is treating the calculator’s first number as the answer.
It isn’t.
It’s a starting point.
Many borrowers focus only on principal and interest and forget about property taxes, insurance, PMI, HOA dues, maintenance, and closing costs.
Another mistake is using an unrealistic interest rate.
A tiny rate difference can change a long-term loan by thousands of dollars.
Common Mistakes
- Ignoring property taxes
- Forgetting homeowners insurance
- Leaving PMI out of the calculation
- Ignoring HOA fees
- Using the maximum lender approval as the budget
- Comparing different loan terms without adjusting the loan amount
- Forgetting closing costs
- Assuming rates never change
- Treating estimated results as guaranteed offers
- Making aggressive extra payments without an emergency fund
The CFPB recommends reviewing the formal Loan Estimate provided by the lender. That document gives you more reliable information about your actual loan costs than a generic online estimate.
For 2026, FHFA set the baseline conforming loan limit for a one-unit property at $832,750 in most U.S. counties, with higher limits in designated high-cost areas.
That does not mean every borrower should target that amount.
It simply shows why loan limits and property location can matter when comparing financing options.
Direct Answer: The biggest mortgage-calculator mistake is ignoring costs outside principal and interest.
Key Takeaway
- Check taxes, insurance, PMI, and HOA fees.
- Use current rate information.
- Confirm estimates against your lender’s Loan Estimate.
A good calculator gives you a realistic range; your lender provides the formal loan terms.
Can You Use Google or Free Mortgage Calculators?
Yes.
People often search mortgage calculator USA Google or mortgage calculator USA free because they want a fast answer without creating an account.
That makes sense.
For an early estimate, a free online calculator can be perfectly useful.
The trick is knowing what the tool includes.
A simple mortgage calculator USA may only calculate principal and interest. A more advanced tool can estimate taxes, insurance, PMI, HOA fees, and extra payments.
The CFPB itself suggests consumers can use online mortgage calculators when estimating affordability.
But you should not stop there.
When you get serious about a property, compare the calculator’s estimate with your lender’s Loan Estimate.
What About “How Much Can I Borrow?”
The search mortgage calculator USA how much can I borrow is slightly different from asking how much you should spend.
Borrowing capacity depends on factors such as:
- Income
- Existing debt
- Credit profile
- Down payment
- Interest rate
- Loan type
- Property costs
- Lender requirements
A calculator can help you estimate a range.
It cannot promise approval.
Direct Answer: Free online mortgage calculators are useful for early planning, but formal borrowing capacity comes from a lender’s underwriting process.
Key Takeaway
- Free calculators are excellent for early estimates.
- Advanced calculators provide a fuller housing-cost picture.
- Do not confuse estimated borrowing capacity with loan approval.
Use free tools to prepare for the conversation with your lender, not to replace it.
What Should You Know About Refinancing and Mortgage Payoff?
A mortgage refinance calculator USA helps compare your current mortgage with a new loan.
The goal is not simply to find a lower interest rate.
You need to consider the complete refinancing cost.
Suppose your new mortgage lowers your payment by $300 per month.
That sounds great.
But if refinancing costs $6,000, your simple break-even point would be:
$6,000 ÷ $300 = 20 months
If you expect to keep the loan longer than that, the savings may become more meaningful. If you move before reaching the break-even point, refinancing may not deliver the benefit you expected.
Mortgage Payoff Calculations
A mortgage payoff calculator USA can also help you estimate how quickly you could eliminate your balance.
You can test:
- Current payment
- Extra monthly payment
- One-time lump-sum payment
- New interest rate
- Remaining loan term
This is particularly useful for homeowners who want to become mortgage-free earlier.
But remember that your lender’s actual payoff amount may include interest through the payoff date and other applicable charges.
Direct Answer: Refinancing and payoff calculators help compare different strategies, but you should include fees and confirm final figures with your lender.
Key Takeaway
- Calculate refinancing break-even time.
- Compare total costs, not just monthly savings.
- Verify the final payoff figure with your lender.
A lower payment is only useful when the complete refinancing math works in your favor.
Mortgage Calculator USA: Beginner vs. Experienced Homebuyer
A first-time buyer usually needs simplicity.
An experienced homeowner may want deeper scenario testing.
| Beginner | Experienced |
|---|---|
| Monthly payment | Total interest |
| Down payment | Extra principal |
| Loan term | Refinancing break-even |
| Property tax | Payoff date |
| Insurance | Multiple rate scenarios |
| PMI | Investment opportunity cost |
| Basic affordability | Detailed cash-flow planning |
A beginner might ask, “Can I afford this house?”
An experienced buyer may ask, “What happens if I pay an extra $300 every month, refinance after five years, and invest the difference?”
That second question produces better financial decisions.
Neither approach needs to be complicated.
Start simple.
Then add detail when the decision becomes real.
Direct Answer: Beginners should focus on total monthly affordability, while experienced borrowers can use calculators for deeper payoff and refinancing strategies.
Key Takeaway
- Start with the basics.
- Add advanced scenarios as needed.
- Never let complexity hide the actual decision.
The best mortgage calculation is the one you can understand and act on.
What Are the Most Common Questions About Mortgage Calculators?
How much is a $400,000 mortgage per month?
Answer: It depends on the interest rate, loan term, taxes, insurance, mortgage insurance, and other costs. At a hypothetical 7.28% rate over 30 years, $400,000 produces roughly $2,737 per month in principal and interest before taxes and insurance.
What is the best mortgage calculator USA?
The best tool is one that lets you enter your loan amount, rate, term, taxes, insurance, mortgage insurance, and extra payments. The more complete the inputs, the more useful the estimate.
Can I calculate how much I can borrow?
Yes, an affordability calculator can provide an estimate based on income, debt, down payment, rate, and housing costs. However, only a lender can determine whether you qualify for a specific mortgage.
Does paying extra on my mortgage save money?
Usually, reducing principal faster means paying less interest over time. The exact savings depend on your loan balance, interest rate, payment schedule, and how your lender applies additional payments.
Should I choose a 15-year or 30-year mortgage?
A 15-year mortgage generally costs more each month but can reduce total interest. A 30-year mortgage usually offers a lower monthly payment but takes longer to repay. Compare both against your budget.
Myth-Busting: What Do Mortgage Calculators Get Wrong?
Myth 1: “The calculator says I can afford it, so I should buy it.”
Not quite.
A calculator cannot understand your job stability, emergency fund, childcare costs, travel plans, or personal comfort level.
Myth 2: “The monthly payment is all that matters.”
Nope.
Two loans can have similar monthly payments but very different total interest costs.
Myth 3: “A lower interest rate always means a better mortgage.”
Not necessarily.
A loan with a lower rate may come with different fees, points, or terms.
Compare the complete loan cost.
Myth 4: “Extra payments are always the smartest move.”
Not automatically.
If you have expensive credit card debt or no emergency savings, those issues may deserve attention first.
Myth 5: “State taxes don’t matter to mortgage calculations.”
They can matter a lot.
Your principal-and-interest formula may stay the same, but your total cost of owning a home can change significantly by location.
Quick Mortgage Calculator USA Checklist
Before trusting your estimate, check these items:
- Home price entered correctly
- Down payment entered correctly
- Loan amount verified
- Current or realistic interest rate used
- Correct loan term selected
- Property taxes included
- Homeowners insurance included
- PMI or mortgage insurance considered
- HOA fees considered
- Closing costs reviewed
- Extra-payment scenario tested
- Monthly payment compared with your actual budget
- Lender’s Loan Estimate reviewed before committing
This checklist takes only a few minutes.
It can prevent a surprisingly expensive mistake..
Conclusion: Use Mortgage Math Before You Shop
A mortgage calculator USA can save you from one of the most common home-buying mistakes: choosing a house based on price alone.
The real number is your total monthly housing cost.
That means principal, interest, taxes, insurance, mortgage insurance, HOA fees, and other recurring expenses.
Use a calculator to test several scenarios. Try different down payments, rates, loan terms, and extra payments. Then compare those estimates with your real household budget.
When you are ready to apply, use the lender’s Loan Estimate to verify the numbers.
And remember, a calculator is not here to tell you what house to buy.
It is here to show you what your choices actually cost.
Bottom Line
A mortgage calculator USA is one of the simplest ways to understand your potential mortgage payment before making a major financial decision. Start with the loan amount, interest rate, and term. Then add taxes, insurance, PMI, HOA fees, and extra payments for a more realistic picture. Compare 15-year and 30-year options, test different down payments, and calculate refinancing or payoff scenarios when useful. Most importantly, use the result as a planning tool rather than a guarantee. Your final mortgage terms depend on your lender, financial profile, property, loan type, and current market conditions.
Ready to run the numbers? Enter your home price, down payment, interest rate, and loan term into a mortgage calculator, then test a few different scenarios before you contact a lender. If this guide helped, share it with someone preparing to buy a home.
References
- Consumer Financial Protection Bureau (CFPB), How Do Mortgage Lenders Calculate Monthly Payments?
- Consumer Financial Protection Bureau (CFPB), Loan Estimate Explainer.
- Fannie Mae, Mortgage Calculator and Mortgage Affordability Calculator.
- Freddie Mac, Primary Mortgage Market Survey (PMMS).
- Federal Housing Finance Agency (FHFA), 2026 Conforming Loan Limit Values.
- U.S. Department of Housing and Urban Development (HUD), FHA Mortgage Insurance Premium Guidance.